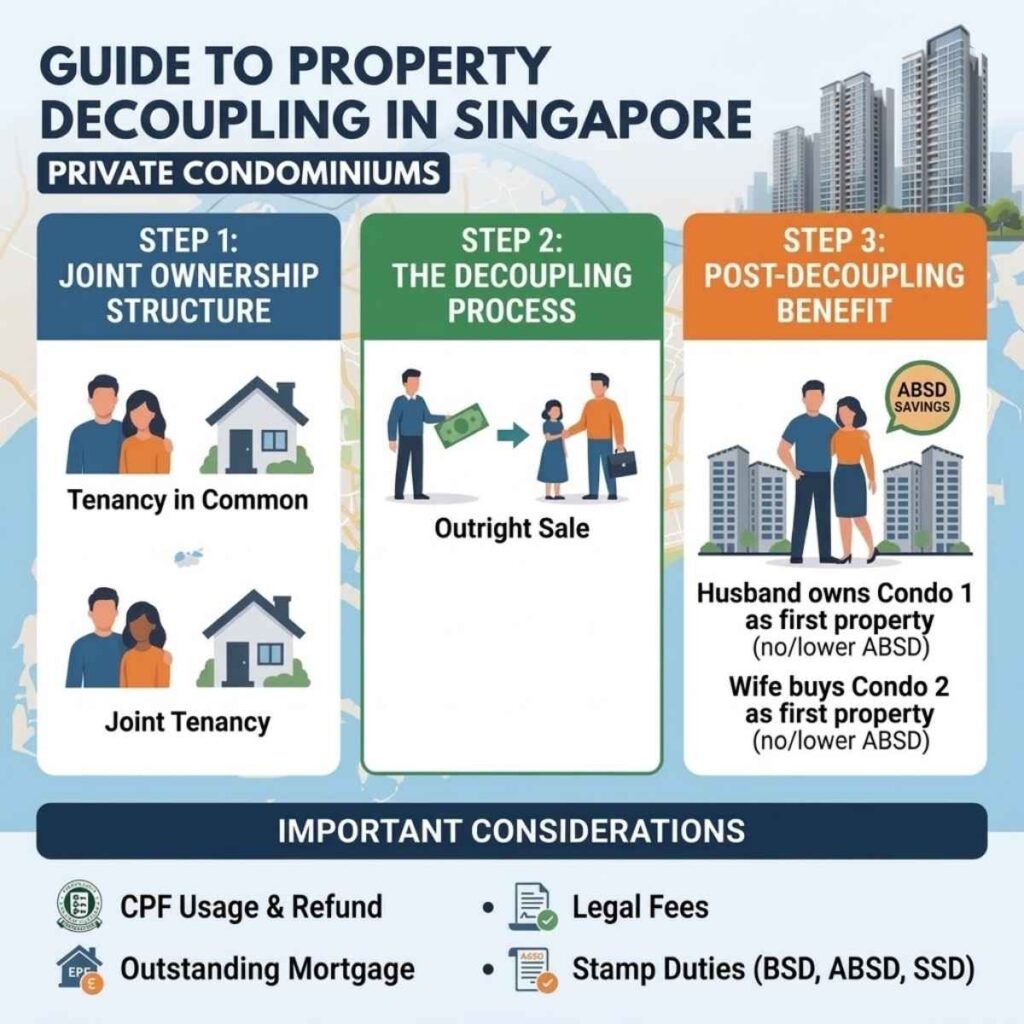
No. Selling the property and buying two, each in one name, reaches the same place: a home in one name and a free name for the next purchase. Each route has two real advantages.
Selling puts the whole property in play. A decoupling can release real funds to the exiting owner, depending on the valuation of their share, the loan against it, and any CPF they used, which returns to their CPF account first.
A sale works on the whole property instead, and puts two names in front of two first housing loans.
Which route leaves you better placed depends on your valuation, your loan and how you each paid, so it needs a proper calculation on your own figures before either is chosen.
A sale refunds both CPF accounts in full and puts two clean names in front of two first housing loans.
Selling lets you change the asset. Decoupling keeps you in the property you already own, which helps only if it is one you would still choose.
Decoupling keeps a good asset. If the home suits you and its location works, replacing it with something of the same quality later may cost more than keeping it.
That is a real saving, and it is easy to underweight.
Decoupling is less disruptive. There is no sale commission, no moving twice, and no stretch between homes.
The full side-by-side is in our guide to selling one property and buying two).